The W2 vs. 1099 CRNA Rate Calculator
Tools
The W2 vs. 1099 CRNA Rate Calculator
What your package is actually worth per hour
To truly compare a W2 role with a 1099 role, you need to know what your W2 hourly rate is. To get this number, you need to weigh the total benefits you get from your W2 job. This includes your salary, plus your bonus, plus your 401k match, plus what your employer pays toward your health insurance, plus your malpractice coverage, plus your PTO, and any other bonuses or benefits your job offers you. When a 1099 offer comes in, none of that is included. You’re comparing a full package to a bare rate and calling it apples to apples.
We built a calculator to fix that.
What it actually does
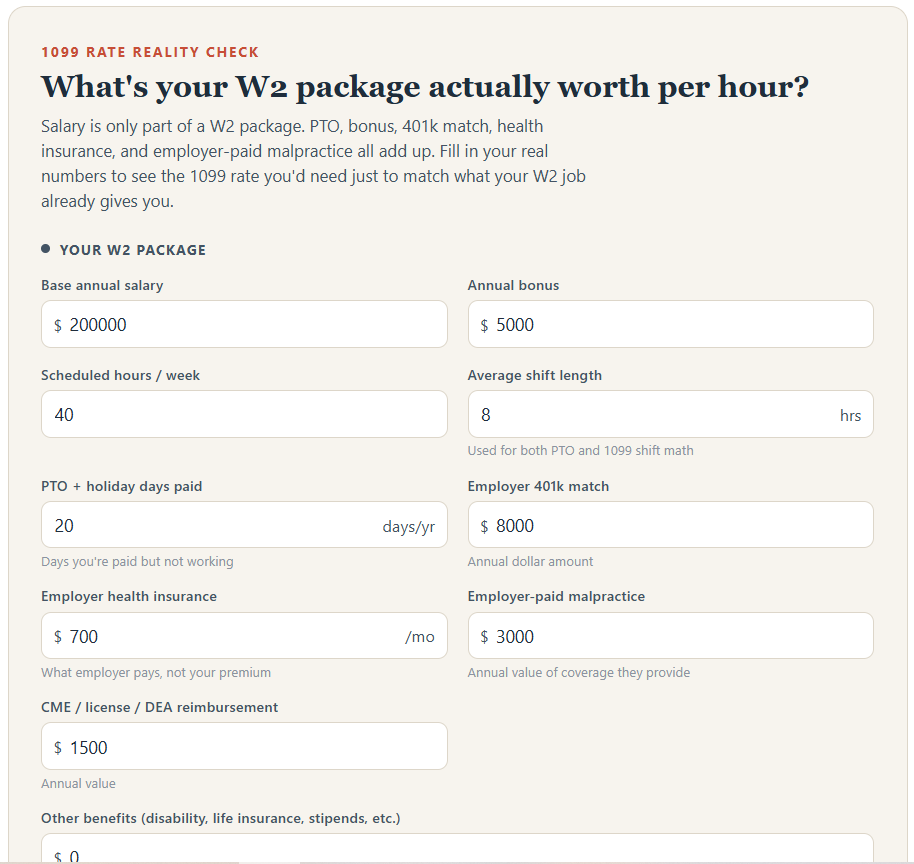
You put in your real W2 numbers — salary, bonus, hours, PTO days, 401k match, health insurance contribution, employer-paid malpractice, CME/license reimbursement — and it converts your whole package into a single true hourly value. Not just taking your salary value and dividing it by 2,080 hours as the common advice is to do.
Then it does the same on the 1099 side. It takes the offered rate and tells you the rate you’d actually need to match your W2 package — factoring in the extra 7.65% self-employment tax you now owe that your W2 employer was previously covering, plus any costs you’d be taking on yourself, like self-funded malpractice insurance if the facility doesn’t provide it.
How to use it
- Pull your actual numbers — your pay stub and open enrollment/benefits summary will have most of what you need (base salary, bonus, 401k match, employer’s health insurance contribution)
- Estimate PTO and holiday days paid, and your typical shift length
- If you don’t know whether your employer covers malpractice insurance and what it’s worth, that’s worth an email to HR — it’s often a bigger number than people assume, typically a few thousand dollars a year
- Enter the 1099 rate you were offered and how many shifts a year you’re actually planning to work
- The calculator shows your breakeven rate and tells you, in plain terms, whether the offer clears it
1099 Rate Reality Check
What’s your W2 package actually worth per hour?
Salary is only part of a W2 package. PTO, bonus, 401k match, health insurance, and employer-paid malpractice all add up. Fill in your real numbers to see the 1099 rate you’d need just to match what your W2 job already gives you. Results update live as you type — nothing is gated.
Opens your email app with your numbers prefilled — no signup, and nothing is sent anywhere until you hit send.
“Breakeven” starts from your total W2 package value per hour actually worked (salary, bonus, 401k match, health insurance, employer-paid malpractice, CME/license reimbursement, and other benefits — spread only across hours you work, since PTO days are paid without being worked). It then adds roughly 7.65% — the employer-side payroll tax you’d otherwise have covered for you — plus any 1099-side costs you’re covering yourself, like self-funded malpractice, amortized across your planned shifts. Income tax itself is left out since it applies at roughly the same rate to both income types. This is a planning estimate, not tax or legal advice — confirm the real numbers with a CPA before deciding.
A word on what this doesn’t cover
This calculator isolates the math that’s specific to comparing a W2 package to a 1099 rate — benefits value and self-employment tax. It doesn’t model your income tax bracket, because that part applies at roughly the same rate to both types of income and mostly cancels out of the comparison. It’s a planning tool, not a substitute for a CPA looking at your actual return.
It also won’t tell you whether the shift is worth it for reasons that have nothing to do with money — schedule fit, whether it conflicts with your current contract’s non-compete, or whether you just don’t want to give up a Saturday. That part’s still on you.
But if the only question in front of you is “is this rate actually good,” this gets you a real answer instead of a gut-check on a bigger-looking number.
Moonlighting as a 1099 CRNA
The complete guide to picking up 1099 shifts while W2 — contracts, credentialing, taxes, and what to watch for before you sign.
Read the moonlighting guideNew to the 1099 world?
Start Here walks through the whole evaluation — the math, the taxes, and the business setup — in the order that actually makes sense.
Start hereEducational disclaimer: this calculator is a planning tool for educational purposes only — not tax, legal, or financial advice. Confirm the real numbers with a CPA or qualified professional before making decisions.
2 Comments